How satellite infrastructure, connectivity, and data services are drawing renewed attention from institutional capital
The launch is the part of the space economy that attracts the cameras. The commercial test comes later, when equipment in orbit must deliver a connection that a customer will pay for, information that improves a decision, or a service reliable enough to support everyday operations. Between those two events lies the question increasingly relevant to institutional capital: how does the ability to reach space become a durable business?
The economic foundations are already substantial. In Space Economy at a Glance 2026, the Organisation for Economic Co-operation and Development (OECD) describes satellite systems as infrastructure supporting transport, energy, communications, agriculture, and other essential activities. Their importance extends beyond the revenues earned by companies conventionally classified as space businesses. A satellite can contribute to the productivity of a shipping operator, an agricultural enterprise, or a communications network whose customers rarely consider where the underlying service originates.
Investment is responding to that reach, although the figures require interpretation. Specialist investor Seraphim recorded $20.8 billion of private SpaceTech investment in the third quarter of 2026, with a single $10 billion Blue Origin financing accounting for almost half the total. The concentration is as informative as the scale. These are measures of capital entering businesses within the tracker’s definition, rather than evidence of profits already earned or returns available to every investor. The institutional opportunity begins with understanding what that capital is financing.
The Business Beneath the Launches
A substantial commercial market exists without relying on projections for lunar settlements or distant resource extraction. The Satellite Industry Association (SAE) estimates that the commercial satellite industry generated $303 billion in revenue during 2025, encompassing services, manufacturing, launch, and ground equipment. Its latest report also records a 62% increase in satellite-broadband subscribers over the previous year. These industry estimates describe an operating economy with established customers, even as new technologies and competitors change its composition.
Connectivity is one of its most tangible services. Satellites can reach ships, aircraft, remote communities, and locations where terrestrial networks are costly or impractical to deploy. They can also provide an additional communications route when ground infrastructure is disrupted. The International Telecommunication Union identifies these applications as important uses of satellite systems, alongside their contribution to observation, weather monitoring, and geospatial information. The customer is purchasing coverage or continuity, rather than participation in a space program.
Earth observation provides another route from technical capability to commercial usefulness. Work supported by the European Space Agency (ESA), such as EO-INSURE, examines how satellite imagery, weather information, and field-level data can help agricultural insurers verify crop damage. Its stated purpose is to establish the technical and economic feasibility of integrating those indicators into insurance workflows. The example is valuable precisely because it identifies a specific decision that the information is intended to improve; it is not evidence that every imagery business has already established profitable demand.
For investors, the inference is that the volume of data collected is an incomplete measure of commercial potential. A useful analysis must arrive in time, be sufficiently reliable, and fit the customer’s existing processes. An insurer may value a clearer assessment of damage more than a higher-resolution image that cannot be interpreted efficiently. The business opportunity lies in converting technical capability into a service whose benefit can be explained, priced, and repeatedly delivered.
This creates a broader investment perspective than the familiar search for the next successful launch company. An enterprise can participate through components, ground systems, software, or specialized analysis without owning a rocket. The most visible hardware may enable the activity, while a different part of the supply chain develops the customer relationship and earns the associated revenue.
An Industry With Several Business Models
The term “space economy” groups together businesses that should not be valued or financed as though they were interchangeable. ESA distinguishes upstream activities, including manufacturing and launch, from downstream markets such as satellite communications, Earth observation, and navigation-related products and services. That distinction is a useful starting point, although considerable variation remains within each category. A hardware manufacturer and a subscription-based data provider may share an industry label while confronting different costs, customers, and competitive pressures.
For analytical purposes, consider three businesses. A component supplier must demonstrate that it can manufacture reliably and secure repeat orders. A network operator must turn deployed capacity into paying usage while funding maintenance and renewal. An analytics company must show that its interpretation of data remains valuable enough for customers to renew their contracts. The relevant questions concern manufacturing economics, network utilization, and customer retention, respectively. Technical sophistication alone does not answer any of them.
An October 19, 2026 announcement illustrates how these roles may become more distinct. Deutsche Telekom, Orange, Telefónica, and Vodafone signed a letter of intent to explore a possible joint bid for European mobile-satellite spectrum. Under the proposed arrangement, the operators would establish ground infrastructure and coordination functions, while a satellite partner, still to be selected, would provide the constellation. The announcement describes an exploratory initiative, not a completed network or an assured revenue stream.
The proposal is nevertheless commercially instructive. It separates access to customers and terrestrial networks from ownership of the assets in orbit. It suggests a model in which established distribution capabilities could be combined with specialist satellite expertise, subject to agreements and execution still to come. For a capital provider, the underwriting would need to follow those responsibilities: which party builds, which party sells, and which party bears the consequences when performance falls short.
Such arrangements also complicate any assumption that exposure to several space businesses automatically creates diversification. A manufacturer, launch provider, and network operator could all depend on the same major deployment program. The investment analysis should examine those commercial dependencies before treating separate company names or allocation categories as independent sources of return.
Financing Capability Into Commercial Service
The financing challenge begins with the distance between a demonstrated technology and dependable cash flow. The OECD identifies long development cycles, substantial technical risk, and uncertain revenue prospects as continuing obstacles for space start-ups, particularly in manufacturing and launch. These characteristics can sit awkwardly with investors’ desired holding periods. Capital may be needed well before a business has established the operating record on which conventional lending normally relies.
A hypothetical network developer makes the problem clear. It may need to pay manufacturers, arrange launch capacity, build ground infrastructure, and obtain permissions before customers can use the service. Delays can therefore consume cash while postponing receipts. The financing structure should allow for that sequence rather than assume that technical milestones, customer activation, and revenue collection will occur simultaneously. A credible deployment plan needs a credible funding plan for the periods when the schedule slips.
Institutional financing is beginning to address more of the supply chain. In July 2026, Intesa Sanpaolo, the European Investment Bank, and ESA announced a two-year arrangement intended to make approximately €300 million in new financing available to businesses across Italy’s aerospace supply chain. The initiative combines European funding and risk-sharing instruments with banking capacity and technical expertise. The figure describes financing the arrangement aims to enable, not an amount already disbursed to operating companies.
The significance is broader than the program’s size. Specialist technical assessment can help lenders evaluate businesses whose capabilities are difficult to judge through conventional collateral measures alone. Risk-sharing arrangements can alter how financing is distributed without removing the need to assess repayment. The opportunity for banking lies in making technically complex enterprises financially understandable, with the remaining risks assigned explicitly.
Public customers can also help bridge the development period. OECD research identifies procurement, grants, co-funding, and anchor-customer commitments as mechanisms that can establish demand and support private financing. Their value depends on the actual arrangement. An expression of public interest, a framework agreement, and a funded purchase obligation provide different foundations for a revenue forecast. The customer’s strategic importance does not make every expected payment unconditional.
Continuing investment deserves equal attention. Eutelsat’s September 2026 announcement of plans to procure 229 additional OneWeb satellites linked the proposed expenditure to service continuity and enhanced capacity, with authorization given for initial industrial work. The example shows why the economics of an operating constellation cannot be assessed solely through its first deployment. Sustaining the service may require further manufacturing, launches, and associated infrastructure over time.
For an investor, the resulting calculation should distinguish expansion from renewal. A business may report rising revenue while needing substantial expenditure to preserve the capacity already supporting that revenue. The useful measure is the cash available after the investment required to sustain competitive service, alongside the cost of financing the next stage. Long-term demand can be attractive while the route to distributable cash remains demanding.
Strategic Importance and Investment Discipline
Governments remain central to the sector’s development through research, procurement, regulation, and support for commercial activity. The OECD’s 2026 assessment emphasizes that growing private participation changes the interaction between public and private institutions rather than making public involvement disappear. For investors, this creates opportunities to support capabilities with identifiable demand, but also makes the terms and durability of public participation part of the commercial analysis.
The regulatory geography is especially important because physical coverage and permission to operate are separate matters. The International Telecommunication Union (ITU) explains that satellite licensing remains a national responsibility, within an international framework governing spectrum and associated orbital resources. A proposed service must therefore be evaluated against the permissions and coordination arrangements relevant to its operations. The fact that a satellite can reach a territory does not establish that the operator can serve every customer there on its preferred terms.
Operational risk also extends beyond the performance of an individual spacecraft. The European Space Agency’s (ESA) 2026 Space Environment Report warns that growing traffic and insufficient removal of defunct objects from congested orbits are increasing collision risks. Its analysis makes orbital sustainability an issue for the continuity of commercial services, as well as for future space activity. Avoidance capabilities, end-of-life planning, and arrangements for replacing lost capacity consequently belong within a financial assessment.
These concerns should sharpen the investment case rather than replace it with an account of everything that might go wrong. A lender would want to understand how an interruption affects contractual receipts and whether insurance responds to the relevant loss. An equity investor would examine the resources available to restore service and retain customers. Both would need to distinguish a manageable disruption from a failure that undermines the business’s commercial premise.
A useful downside scenario need not assume technological collapse. Demand might grow more slowly than forecast, customers might resist expected prices, or competitors might add capacity faster than anticipated. In that scenario, the service can remain economically useful while the original valuation proves too generous. The analytical task is to establish whether the business and its financing can withstand a less favorable outcome without relying continuously on new capital.
The form of the investment determines how that outcome reaches the portfolio. An ownership stake in a developing operator, a loan to an established supplier, and an interest in a diversified fund represent different claims and different liquidity arrangements. An institutional allocation should specify which exposure is intended, how losses could arise, and whether its horizon is compatible with the capital committed. A shared association with space is not sufficient justification for treating these instruments alike.
An Investment Case Grounded on Earth
The constructive case rests on an expanding range of useful services and a broader ability to finance the businesses delivering them. Reliable connectivity in difficult locations, better information for commercial decisions, and specialized equipment supporting operating networks all provide identifiable starting points. They allow analysis to move beyond projections of the total future space economy toward customers, contracts, margins, and the expenditure required to remain competitive.
The distribution of economic benefits will matter as much as their aggregate size. A shipping company may capture value through improved operations, while a communications customer benefits from lower prices or broader coverage. Those gains do not necessarily accrue to the company that financed the satellite. Investors need to establish where bargaining power resides, what the service can earn, and how much of the value created can reasonably remain with the business they own or finance.
For institutional capital, this leaves room for informed participation without requiring a forecast of every technological milestone. Established services and developing capabilities can be evaluated separately, with different expectations for liquidity, evidence, and time to profitability. The sector’s breadth creates more possible points of entry, but makes selectivity more important. The strongest proposition will explain why a particular business can serve a real need on terms that support its capital structure.
Space will continue to command attention through ambitious engineering and highly visible launches. Its enduring investment significance will be established in less dramatic transactions: a customer renewing a service, a supplier delivering on schedule, an operator generating cash after necessary reinvestment. The launch demonstrates that the equipment can reach its destination. The institutional case is made when the business it supports earns its place in the economy below.
About Berkeley Financial
Berkeley Financial is an international financial group providing institutional banking, private banking, custody, and cross-border financial solutions. Its approach emphasizes governance, relationship-driven execution, and the requirements of institutions and sophisticated clients with international financial needs.
Disclaimer
This article is provided for informational purposes only and does not constitute investment, legal, tax, regulatory, or financial advice, nor an offer or recommendation concerning any security, fund, financing arrangement, or investment product. References to companies and transactions are illustrative and do not imply Berkeley’s participation, affiliation, or endorsement. Sector investment figures and revenue estimates reflect the definitions and dates of the cited sources. Space-related investments may involve substantial technological, operational, regulatory, credit, liquidity, valuation, and concentration risks, including loss of principal. Investment decisions should consider the relevant documentation, costs, objectives, liquidity requirements, and capacity to bear loss.
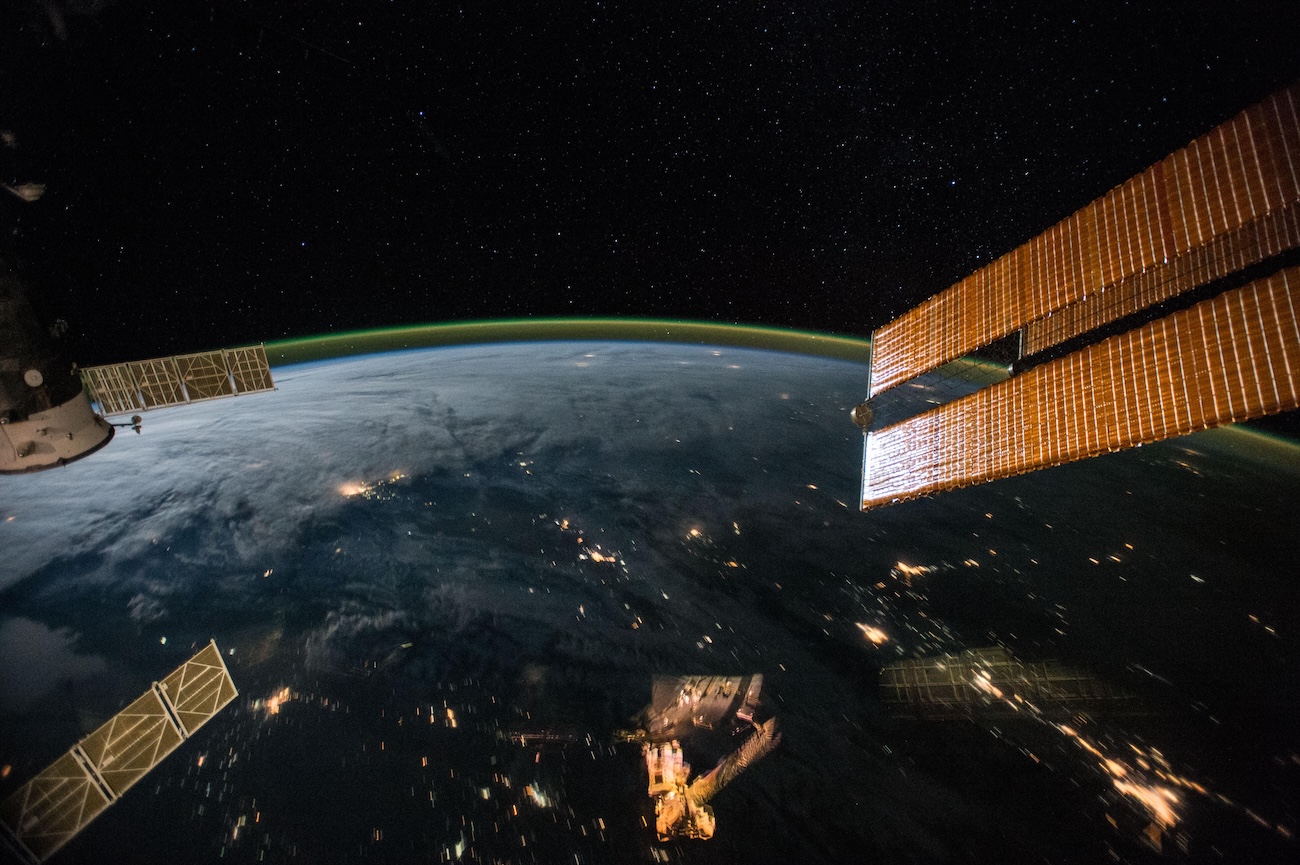
Image courtesy of the Earth Science and Remote Sensing Unit, NASA Johnson Space Center. Image ID: ISS042-E-19653
References
- Organisation for Economic Co-operation and Development (OECD). The Space Economy at a Glance 2026. OECD Publishing, Paris, September 9, 2026. Particularly Chapter 1, “Strategic Capabilities and Competitiveness in the Space Economy.”
- OECD. “Governments Remain Central to Fostering Competitiveness and Innovation in the Space Economy as Private Investment Grows.” Press release, September 9, 2026.
- Seraphim Space. Seraphim SpaceTech Investment Tracker, Q3 2026. Quarterly review of global private SpaceTech investment, including financing volumes, deal activity, and sector classifications.
- Satellite Industry Association (SIA). “Affordability and Productivity Drive Historic Satellite Industry Growth: Satellite Industry Association Releases the 29th Annual State of the Satellite Industry Report.” Press release, May 13, 2026. Report produced by BryceTech, covering industry performance during 2025.
- International Telecommunication Union (ITU). “Satellite Regulation and Coordination.” Institutional backgrounder on satellite applications, national licensing, spectrum management, and international coordination.
Sources accessed October 23, 2026. Market figures reflect the definitions and reporting periods used in the original publications. Company announcements are cited as illustrative examples and do not imply Berkeley’s participation, affiliation, or endorsement.